How to Do a Development Appraisal in Excel (With an Example)
How to Do a Development Appraisal in Excel (With an Example)
A development appraisal answers two simple questions: does this scheme make enough profit, and how much can I afford to pay for the site? You start with what the finished building will be worth, take off every cost and the profit you need, and whatever is left is your land price.
It sounds like a lot, but it is just a list of lines in a sensible order. In this guide we will build one together, with a UK office example you can copy into Excel.
The quick version
A development appraisal starts with the value of the finished scheme (GDV) and works backwards to a land price. That land price is called the residual land value.
The main lines are GDV, purchaser's costs, construction, fees, contingency, letting costs, finance, land costs and your profit.
Profit can be measured on GDV or on cost. The same scheme gives different percentages, so always say which one you mean.
Land is the balancing figure, so small changes in value or cost move it a lot. Always test a few sensitivities.
What is a development appraisal?
It is a financial model that tests whether a development stacks up. Developers use it to decide whether to buy a site and how much to bid. Lenders and investors use it to check the risk. Valuers use a version of it, the residual valuation, to value development land.
What goes into one?
Gross development value (GDV): what the finished scheme will be worth. Our guide to what GDV means and how to calculate it explains how.
Purchaser's costs: what a buyer pays on top of the price, such as SDLT, agent and legal fees. In the UK we usually use 6.8% for commercial property. Take this off GDV and you have net development value (NDV).
Construction costs: the build, plus external works.
Professional fees: architects, engineers and project managers, usually a percentage of construction.
Contingency: a cushion for surprises, usually a percentage of construction.
Letting and legal costs: agents and solicitors to let the building.
Finance: the interest and fees on your loan. See how development finance and rolled-up interest work.
Land costs: SDLT, agent and legal fees on the site, plus interest on the land.
Developer's profit: the return you need for taking the risk.
How do you do a development appraisal, step by step?
Decide what you are answering. Either "what can I pay for this site?" or "does this scheme make the profit I need?" Think about who will read it, such as an investment committee or a lender.
Set up the workbook. Keep inputs, calculations and the summary in separate areas, and colour the inputs so anyone can see what can be changed.
Work out the value. Measure the net internal area, then use rent and yield (or units and prices) to get to GDV.
Take off purchaser's costs to reach NDV.
Add the costs: construction, fees, contingency and letting costs.
Add finance. Estimate how long the build and letting will take and how much interest you will pay on the money drawn.
Set your profit target and solve for land. The answer is the residual land value, after land costs and land interest.
Check and test. Make sure everything adds up, then try different values, build costs and yields.
Worked example: a 20,000 sq ft office scheme in the UK
These numbers are for illustration, so use your own assumptions on a real scheme.
Line | Working | Amount |
|---|---|---|
Annual rent | 20,000 sq ft × £30 | £600,000 |
GDV | £600,000 ÷ 6.0% yield | £10,000,000 |
Less purchaser's costs | 6.8% | (£636,704) |
Net development value (NDV) | £9,363,296 | |
Construction | (£4,500,000) | |
Professional fees | 10% of construction | (£450,000) |
Contingency | 5% of construction | (£225,000) |
Letting and legal fees | 15% of annual rent | (£90,000) |
Finance on build costs | 7.5% for 18 months, half drawn on average | (£291,094) |
Developer's profit | 15% of GDV | (£1,500,000) |
Left for land and land costs | £2,307,202 | |
Land costs and land interest | 6.5% purchase costs plus 15% interest (7.5% for two years) | 21.5% of the land price |
Residual land value | £2,307,202 ÷ 1.215 | £1,898,932 |
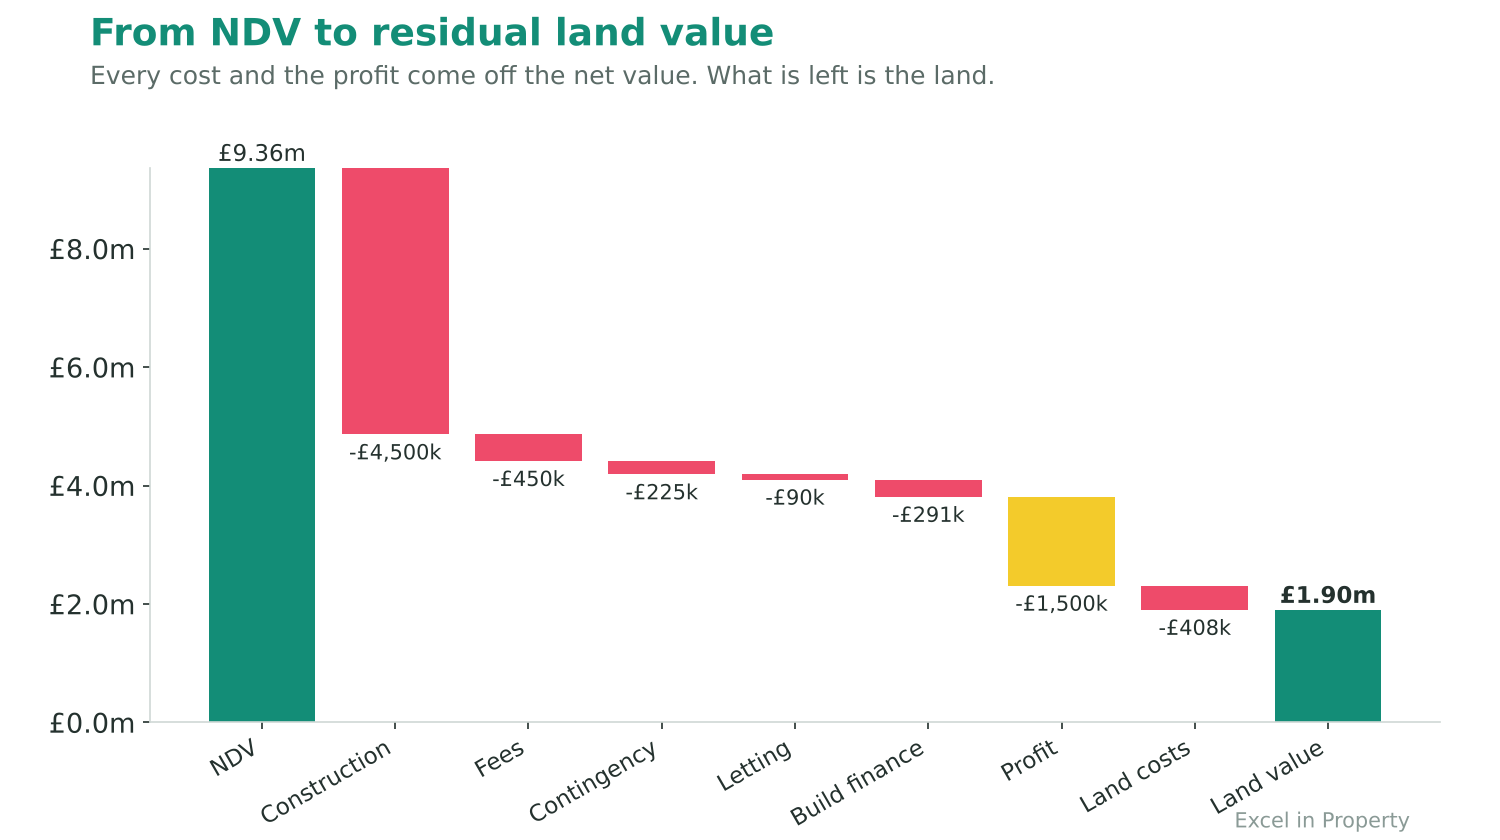
So the most you could pay for the site is about £1.9 million. At that price the land costs are £123,431 and the land interest is £284,840, and everything adds back up to the NDV of £9,363,296. That is your check that the maths works.
Profit on cost or profit on GDV?
Profit on GDV is profit divided by GDV. Profit on cost is profit divided by total cost, including land and finance. In our example the profit is £1.5 million, which is 15% of GDV, 16.0% of NDV and 19.1% of total cost. Same scheme, three different percentages! Always check which one your lender or investment committee uses before you compare results.
How do you estimate finance in a simple appraisal?
A quick residual appraisal estimates finance without a full cash flow. In our example the build costs (construction, fees and contingency) come to £5,175,000. They are drawn gradually over an 18-month build, so on average about half is borrowed for the whole period.
Finance on build costs = £5,175,000 × 7.5% × 1.5 years × 50% = £291,094.
We have left out interest during the letting period to keep things simple. In a real appraisal you would add it, because the whole loan is outstanding while the building is let, and your land value would come down. A development DCF handles this month by month and gives you a more accurate answer.
How do you work out land costs and land interest?
The land price is the thing we are solving for, so land costs and land interest are written as percentages of it. Here, SDLT, agent and legal fees are 6.5% of the land price, and interest is 7.5% for two years, which is 15%. Together that is 21.5% of the land price.
So land price × 1.215 = £2,307,202, which means the land price is £2,307,202 ÷ 1.215 = £1,898,932.
In practice SDLT is charged in bands, so check the current rates on GOV.UK for the real figure.
Residual appraisal or DCF?
A residual appraisal is a snapshot. It uses simple timing and a simple finance estimate to find a land price or a profit. A development DCF models the cash flows month by month: drawdowns, the letting period, the rent, and the sale. It gives you returns such as IRR and the peak equity you need.
A good approach is to use a residual to find a land price, then a DCF to test timing and finance. Our guide to DCF in real estate explains when to use one. Move to a DCF when timing matters, for example with phased construction, pre-lets, a long letting period or a refinance.
Common mistakes to avoid
Comparing profit on GDV with a target set on cost.
Forgetting interest on the land, which is often one of the biggest finance lines.
Leaving out contingency, or setting it too low for an early design.
Forgetting purchaser's costs, or using the wrong ones.
Typing numbers inside formulas, so nobody can see what drives the answer.
Showing one answer with no sensitivities. Here is how to run a sensitivity analysis.
Frequently asked questions
What is a development appraisal?
It is a model that tests whether a development makes enough profit, by comparing the value of the finished scheme with its costs, finance and your target profit.
How do you calculate developer's profit?
Developer's profit is net development value minus all costs. Show it as a percentage of GDV or of total cost, and say which.
What is a good profit on cost?
There is no single number. Lenders and funders set their own minimums depending on risk, scheme type and the market. Many UK schemes are tested at around 15% to 20% on GDV, but check what your funder needs.
Can you do a development appraisal in Excel?
Yes, Excel is the standard tool. Keep inputs, calculations and outputs separate, add checks and run sensitivities.
Want to learn how to do this properly?
In the How to Model a Development: From Residual to DCF course, we build the residual and the full DCF side by side, step by step. It is part of the EiP Academy, which gives you all nine courses plus the Development Appraisal Model from the Model Library.
New to modelling? Start with the Crash Course
